The sourcing layer of cosmetic distribution is gone. Buyers can find factories, compare unit prices, and book freight without anyone’s help, and they know it. What has not gone away is the part of distribution that carries legal risk, holds territory, and consolidates twenty product lines into one purchase order — and most distributors are still pricing the first thing and not the second.
What distributors actually say
“Is the import/export business a dying business? … it’s easy to find suppliers on Alibaba and shipping companies like DHL handle logistics for you”
a post on r/supplychain
“20 years ago it was viable to have a business model where you represented a few factories and pitched their products to buyers. That business has generally gone away”
a reply in the same thread
Read those two quotes together and the diagnosis is already in them. Both describe the same job: representing factories to buyers. Neither describes holding a registration, defending a territory, or running a portfolio. The complaint is accurate — that job is gone — but it is a complaint about one function of distribution, not the whole of it. The people still making margin in this segment are not arguing with the marketplaces. They stopped selling discovery years ago.
Where the number actually comes from
Discovery was three questions: who makes this, what does it cost, and can they ship it to me. Marketplaces answered all three, globally, for free, and they answered them better than any distributor’s sample bag ever did. A buyer in Frankfurt can see forty factories in Guangzhou before lunch and get a freight quote in the same session. When a function becomes free, the margin attached to it goes to zero. That is not a market failure; it is the market working. Any distributor whose value proposition still resolves to “I know a factory” is now charging for something the buyer already has.
What did not commoditise is liability. A marketplace listing cannot hold a product registration in the destination market, and it cannot answer to a regulator when something goes wrong. Under EU rules, someone established in the jurisdiction has to be the Responsible Person, hold the Cosmetic Product Safety Report, and file the CPNP notification — and that someone carries legal exposure, not just paperwork. In the US, the facility registration and listing obligations sit with named parties, not with a platform. This is the part of the chain a factory in another country structurally cannot absorb for the buyer’s market, and it is the part that has a real, defensible cost. When a distributor says “I hold your compliance,” they are selling risk transfer, and risk transfer has never been free.
Exclusivity is the second thing that did not commoditise, and the mechanism is worth understanding. A factory will not grant territory to a single buyer, because one buyer is one order and the factory’s economics depend on many. Granting exclusivity to an end buyer also caps the factory’s reach in that market permanently. A distributor is different: it aggregates demand across many buyers in a territory, which means the factory’s volume in that market goes up, not down, when exclusivity is granted. That is why territory agreements are signed with distributors and not with retailers. The distributor is not inserting itself into the transaction — it is creating the volume condition that makes exclusivity rational for the factory in the first place.
The third is portfolio breadth, and it is the one buyers feel most acutely. A retailer or a brand does not want twenty factories with one SKU each. Twenty factories means twenty sets of documents, twenty compliance files, twenty shipping schedules, twenty quality conversations, and twenty points of failure. They want one supplier with twenty SKUs, one set of paperwork, and one throat to choke. No marketplace solves this, because marketplaces are built to maximise the number of suppliers, not to consolidate them. Consolidation is labour, and labour is a service. That is the third leg of a distribution margin that survives contact with a price comparison.
The tell is in the complaint itself. Look at who is describing distribution as dying: people describing representing factories to buyers. Look at who is thriving: people describing holding compliance and territory, and running a portfolio for accounts that do not want to manage twenty vendors. Same industry, two different jobs. One of them is competing on the thing that is now free, which is a race to the bottom by definition. The other is selling things a marketplace structurally cannot provide — a legal entity in the destination market, a defended territory, and a consolidated order book. The margin follows the second job.
What this means if you are a distributor
- Stop quoting on unit price alone. If your proposal reads like a marketplace listing, you have already lost to a marketplace listing. Quote the compliance file, the territory, and the consolidated shipment.
- Audit what you actually hold. If you are not the named party on registrations, safety reports, or territory agreements, you are still a sourcing agent with extra steps — and you are priced accordingly.
- Count your SKUs per account. A distributor handling one product line per client is a broker. A distributor handling ten to twenty is a portfolio supplier, and that is a different conversation about margin.
- Get the factory’s paperwork in writing before you promise anything to a buyer. Exclusivity that exists only in an email thread is not exclusivity, and certification claims you cannot evidence in an audit are a liability you have just accepted.
- Price the consolidation. The work of pulling twenty SKUs from one source, with one document set and one delivery schedule, has a cost — and it has a value to the buyer that has nothing to do with the factory’s unit price.
How we approach it
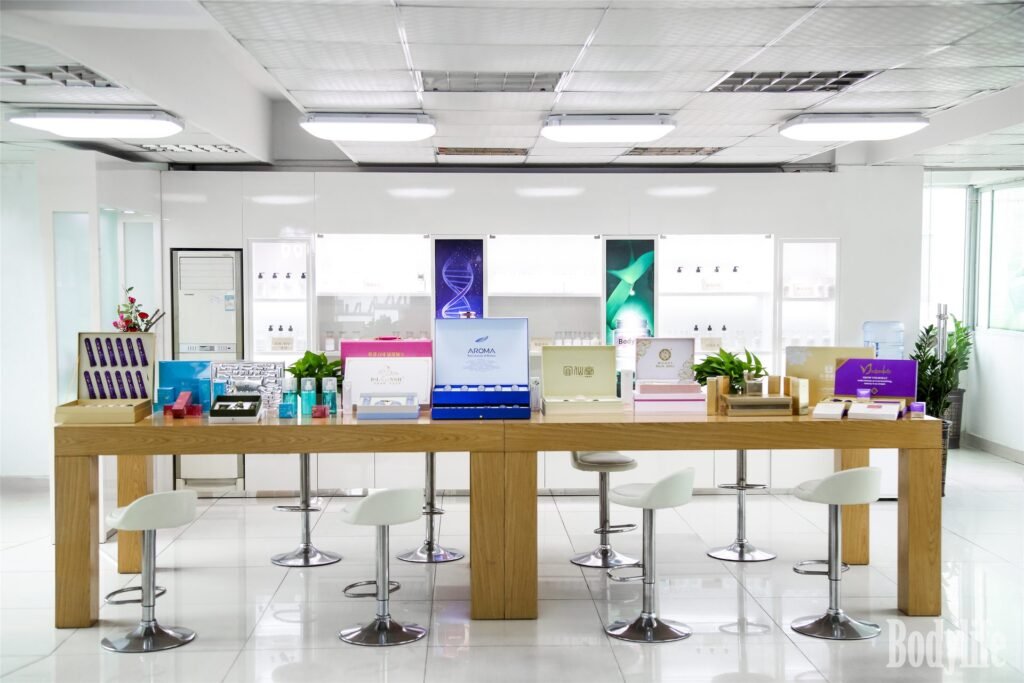
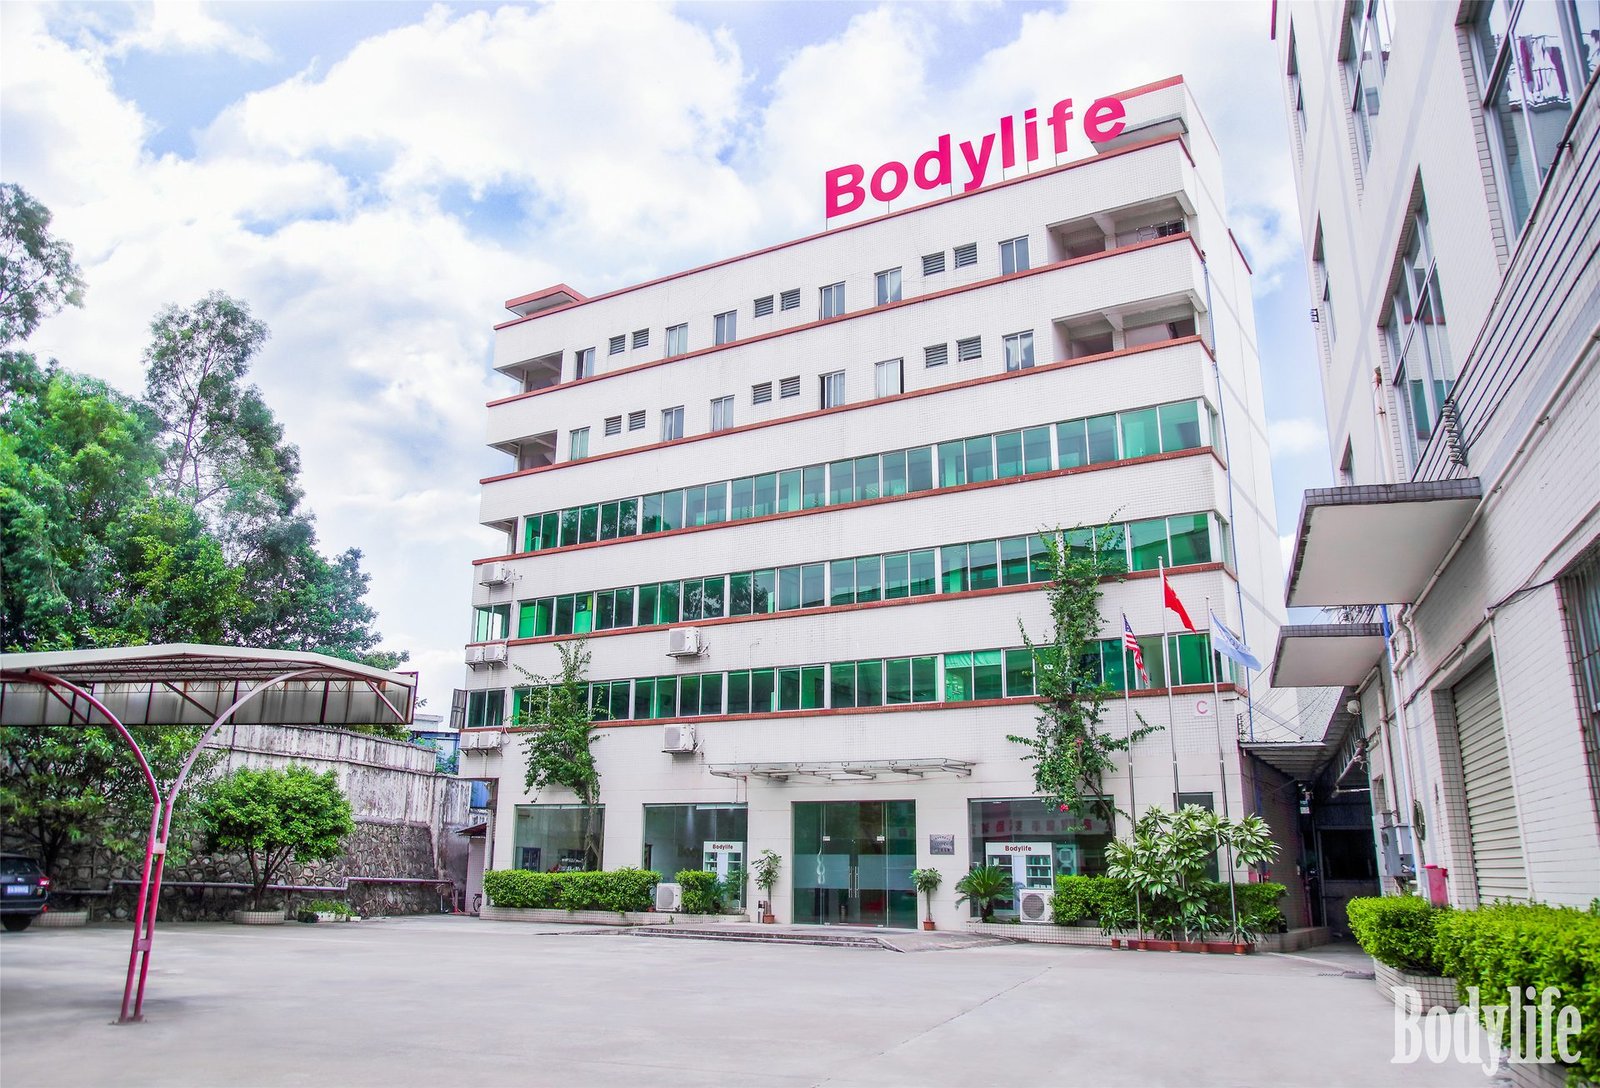
BodyLife has operated for 25 years as a manufacturer, and we work with distributors and importers as the party that supplies the portfolio and the documentation behind it. We do not compete with our distributors for end buyers. The relevant capabilities, stated plainly:
- A library of 500+ white-label formulations, so a single supplier can fill a twenty-SKU portfolio rather than a single product line — including private label body lotion and adjacent body care lines.
- Multi-market compliance documentation covering CPNP and CPSR for Europe and FDA requirements for the US, so registration responsibility can be structured clearly between manufacturer and distributor rather than left ambiguous.
- Facility-level certification — GMP, ISO 22716, ECOCERT, COSMOS, FDA, SMETA, CPNP, CPSR — that stands behind the product in an audit. The full list is on our certifications page.
- Two GMP-certified plants totalling 60,000+ m², 20+ production lines, and annual capacity of 100M+ units, sized for portfolio-level volume rather than single-SKU orders.
- OEM minimum order from 500 units, scalable to 100,000+, with quotation inside 48 hours, sampling in 7–10 days, first order in 20–30 days, and reorder in 7–14 days.
- Every batch tested with a certificate of analysis issued and full chain traceability, backed by an in-house R&D laboratory for formulation, stability, microbiology, and heavy metals.
- Packaging one-stop sourcing including PCR material, with stock packaging supporting small orders.
We also run special-population lines — baby and pregnancy, mature and silver hair, feminine intimate, scalp, men, and pet — because those are the categories distributors get asked for most often and the ones where documentation matters most. More on how we work with the trade is at manufacturing for distributors and importers.
Frequently asked questions
Is distribution still viable?
Yes, but not as a sourcing service. The function of finding factories and quoting their prices is now free and global, so a margin built on that has no floor. Distribution remains viable where the distributor holds regulatory responsibility, defends territory, and consolidates a portfolio for buyers who do not want twenty vendors. Those are services a marketplace cannot perform, and they are priced on risk and labour rather than on information.
What can a distributor offer that Alibaba cannot?
Three things. A legal entity in the destination market that can hold product registration and answer to the authority there. Territory that a factory will grant to an aggregating distributor but not to a single buyer. And consolidation — one supplier, twenty SKUs, one document set, one delivery schedule. A marketplace is built to maximise the number of suppliers; a distributor is built to reduce it, and that reduction is the value.
How do I get exclusivity from a factory?
By being the party that aggregates demand in a territory, not the party that places a single order. A factory grants territory when exclusivity increases its volume in that market, which is what a distributor’s combined order book does. Get the agreement in writing, define the territory and the term, and be clear about what volume commitment sits behind it. Exclusivity that lives only in an email thread is not exclusivity.
Can one supplier cover a whole portfolio?
It can if the supplier’s formulation library and capacity are built for it. BodyLife runs a 500+ formulation white-label library across two GMP-certified plants with 100M+ units of annual capacity, which is sized for portfolio-level volume rather than single-SKU orders. Minimum order starts at 500 units and scales to 100,000+, so a distributor can build a range without committing to container-scale volume on every line.